Is this the moment to buy your Austin home, or the year to wait a little longer? Prices have softened and buyers have more leverage than they have had in years, but mortgage rates have climbed back to 7.40%. Austin's market, once a frenzy of bidding wars, now rewards buyers who run the numbers before they decide.
Key Insights for Buying a Home in Austin Now or Waiting
- Rates have risen: The average 30-year mortgage rate was 7.40% in early October 2026, up from 6.30% a year earlier (Freddie Mac). The Federal Reserve raised its target rate on September 16.
- Prices are soft: The Austin metro median fell 6.4% year over year to $412,000 in August 2026. The City of Austin median was $560,000.
- Buyers have leverage: City of Austin homes closed at 93.3% of list price in August, and active listings give buyers room to negotiate repairs, closing cost credits, and price.
- Waiting is a bet on two variables: Zillow forecast a 4.6% price decline through March 2027, but a rate increase can cost more per month than a price drop saves.
- Hyper-local dynamics matter: Medians range from $254,000 in Caldwell County to $520,000 in Travis County, and each neighborhood behaves differently.
- Time horizon is critical: Buying generally makes more sense if you will stay in Austin five years or more. Shorter timelines tilt toward renting.
This guide walks through the current state of the Austin housing market, what buying now costs compared with waiting, the pros of each choice, and the factors that should guide your decision. If you want to see how Austin compares to a neighbor, read Austin vs. Dallas. If you are wondering whether home prices will keep falling, see our post on Austin home prices.
Austin Market Snapshot
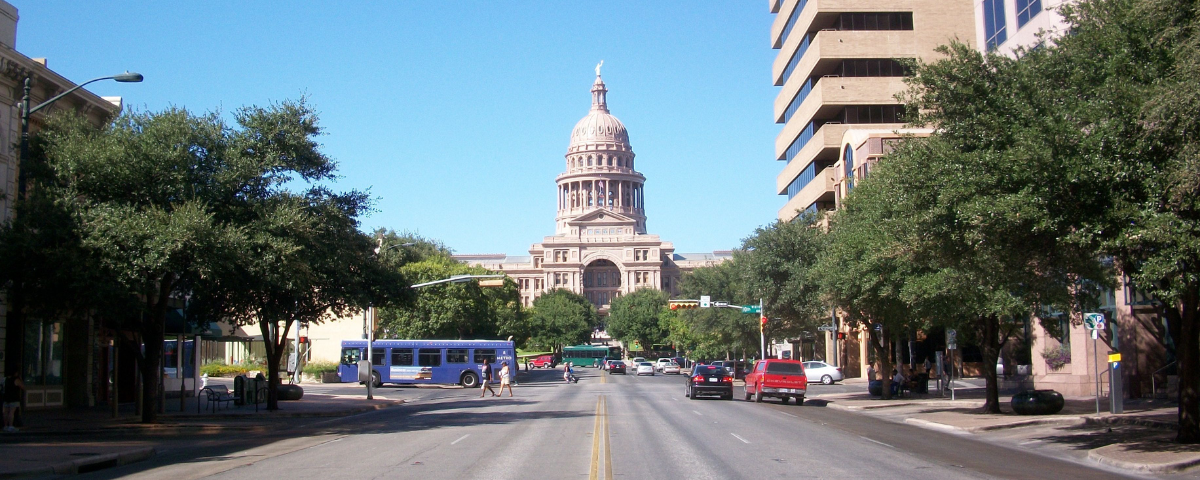
Austin's housing market looks very different from the highs of a few years ago. The bidding wars and relentless price spikes are gone, replaced by a steadier, more balanced market with real opportunities for buyers.
| Measure | August 2026 | Compared with a year earlier |
|---|---|---|
| Median sale price, City of Austin | $560,000 | Not reported |
| Median sale price, Austin metro | $412,000 | Down 6.4% |
| Median sale price, 3 months (Redfin) | $550,000 | Down about 1% |
| Closed sales, City of Austin | 844 | Down 10.3% |
| Pending sales, City of Austin | 814 | Down 9.2% |
| Active listings, City of Austin | 4,554 | Down 14.5% |
| Sale price as a share of list price | 93.3% | Up from 91.6% |
| Average days on market (Redfin) | 57 days | Down from 65 days |
Sources: Hoodline, reporting Unlock MLS Central Texas Housing Report data (MLS only) and Redfin. The two sources use different geographies and time periods, so their figures differ. Last updated October 2026.
Median prices
Home values have cooled from the breakneck growth of the pandemic years. The City of Austin median sale price was $560,000 in August 2026, and the wider metro median was $412,000, down 6.4% from a year earlier (Unlock MLS). The two numbers differ because the metro includes lower-priced suburbs and counties.
Mortgage rates
Borrowing costs are reshaping buyer behavior. The 30-year fixed mortgage rate averaged 7.40% for the week of October 8, 2026, up from 7.28% the week before and 6.30% a year earlier (Freddie Mac). See our guide to the factors that affect mortgage rates for what moves them. Higher rates have slowed the market: closed sales in the City of Austin fell 10.3% year over year in August.
Inventory and negotiating power
There are more homes for sale in Austin than during the boom years, which shifts leverage toward buyers. The City of Austin had 4,554 active listings in August 2026, down 14.5% from a year earlier but still enough to give buyers choices. Homes sold at 93.3% of list price, up from 91.6% a year earlier, and Redfin reports an average of 57 days on market.
Market resilience
Austin is far from fragile. The metro's unemployment rate was 3.9% in August 2026 (BLS), and a strong tech and healthcare economy continues to support long-term demand. As Vaike O'Grady of Unlock MLS put it in the July report, "Deals are happening, prices are holding."
What Buying Now Costs vs. Waiting
The payment math shows why timing is not just about prices. A one-point drop in rates saves more per month than a 4.6% drop in price, and a rate increase can cancel out a price decline entirely.
| Scenario | Price | 30-year rate | Monthly principal and interest |
|---|---|---|---|
| Buy now | $550,000 | 7.40% | $3,046 |
| Same price, at last year's rate | $550,000 | 6.30% | $2,723 |
| Wait: prices fall 4.6%, rates stay flat | $524,700 | 7.40% | $2,906 |
| Wait: rates fall one point, prices flat | $550,000 | 6.40% | $2,752 |
| Wait: prices fall 4.6%, rates rise to 8.00% | $524,700 | 8.00% | $3,080 |
Calculation by Spyglass Realty: 20% down payment, 30-year fixed loan, principal and interest only. Taxes, insurance, and mortgage insurance are extra. The 7.40% rate is the Freddie Mac average for the week of October 8, 2026 (source). The 4.6% price decline is Zillow's forecast through March 2027, issued in May 2026. These are illustrations, not predictions.
At today's rate, a $550,000 home with 20% down costs about $3,046 a month in principal and interest, versus $2,723 at last year's 6.30% rate. If rates rise further while you wait, a lower price may not help. If rates fall, you could refinance later, which is why many agents say to "marry the house, date the rate."
County-by-County Breakdown: Austin Metro Real Estate
The Austin metro covers five counties with different price points and market conditions. Understanding the differences helps you decide where to focus your search.
| County | Median price (July 2026) | Change vs. a year earlier | Active listings | Months of supply* |
|---|---|---|---|---|
| Travis (Austin) | $520,000 | About flat | 6,586 | 5.1 |
| Williamson (Round Rock) | $415,000 | Down 1.2% | 4,258 | 4.4 |
| Hays (Kyle, Buda, San Marcos) | $367,700 | Up about 1% | 1,925 | 5.6 |
| Bastrop | $346,140 | Up 2.3% | 758 | 6.9 |
| Caldwell | $254,000 | Down 16.4% | 269 | 7.1 |
Source: CultureMap Austin, reporting Unlock MLS and Austin Board of Realtors data for July 2026. *Months of supply is Spyglass Realty's calculation: active listings divided by July closed sales. Last updated October 2026.
- Travis County: The most expensive county, with the strongest demand in central neighborhoods and the shortest commutes to downtown and major employers.
- Williamson County: Family-friendly suburbs such as Round Rock, Cedar Park, and Georgetown, with strong schools and better value per square foot.
- Hays County: Kyle, Buda, and San Marcos offer more affordable options and new construction, with longer commutes to central Austin.
- Bastrop County: The highest supply in the metro, which favors buyers, with a more rural feel and limited public transit.
- Caldwell County: The most affordable entry point, though price swings are larger because fewer homes sell.
Buyers priced out of Travis County can save significantly in outlying counties while staying within reach of Austin's job market. Weigh those savings against the longer commute.
Pros of Buying a Home in Austin Now
Buying in today's market feels daunting, but the cooldown has created advantages that did not exist a few years ago.
- Greater negotiating power: Instead of competing with dozens of offers, you may face a handful or none. That gives you leverage for price reductions, seller concessions such as closing cost credits, or rate buydowns.
- Softer prices: With the metro median down 6.4% year over year, the risk of overpaying at a peak is lower, and you start building equity right away.
- Certainty in housing costs: A fixed-rate mortgage locks in your principal and interest. If rates fall later, you can refinance.
- Wealth building: Every payment reduces your loan balance, and even modest appreciation adds up over time.
Pros of Waiting Before Buying a Home in Austin
Not every buyer feels urgency right now, and waiting can be the right call.
- Possible lower prices: Zillow forecast Austin home values falling about 4.6% through March 2027, and high inventory gives some sellers reason to cut asking prices.
- Time to prepare financially: Waiting lets you raise your credit score, grow your down payment, and pay down debt, all of which improve loan terms.
- Flexibility: If you are unsure about your job or how long you will stay in Austin, waiting eases the pressure.
- A chance for rates to ease: If inflation cools, mortgage rates could come down, though the Fed's recent rate increase makes that uncertain.
Choosing to wait does not mean you are missing out. It can mean making space for a smarter move later, as long as you stay engaged so you are ready when the right opportunity appears.
Austin Real Estate Market Forecast
No forecast is certain, but expert predictions and economic indicators provide useful context for your timing.
Price forecast
In May 2026, Zillow projected that Austin home values would fall about 4.6% through March 2027, which on a typical home value of about $508,530 would be a decline of roughly $23,400. Forecasts are updated regularly, so check Zillow for the latest projection before you decide.
Interest rate outlook
The Federal Reserve voted unanimously on September 16, 2026, to raise its target range by a quarter point to 3.75%-4.00%, saying "Inflation remains elevated." Mortgage rates have followed higher, reaching 7.40% in early October. Whether they fall depends on inflation and future Fed decisions, and many analysts see a drop below 6% as the trigger that would bring buyers back in force.
Economic wildcards
- Upside: Faster-than-expected cooling of inflation, a resilient job market, and corporate relocations to Austin.
- Downside: Further rate increases, tech-sector layoffs, rising property taxes, and oversupply from new construction.
How Austin Compares to Other Texas Markets
Austin's price level is higher than the other big Texas metros. Dallas, for example, had a median sale price of about $450,000 in the three months ending September 2026 (Redfin), compared with about $550,000 in Austin. Austin's market has also been softer: Dallas prices were up 3.4% year over year while Austin's were down about 1%. For a full comparison, see Austin vs. Dallas.
Austin keeps real advantages: a strong tech job market, a high quality of life, and limited land to build on because of the Hill Country and the aquifer. Choose Austin if long-term appreciation and your career in tech or creative fields matter most. Consider alternatives if affordability, larger homes, or lower property taxes are your top priorities.
Renting vs. Buying in Austin
| Feature | Renting | Buying |
|---|---|---|
| Typical monthly cost | $1,174 for a 1-bedroom, $1,429 for a 2-bedroom | About $3,046 principal and interest on a $550,000 home with 20% down, plus about $573 in property tax |
| Upfront cost | Deposit and first month | Down payment, closing costs, and inspections |
| Flexibility | High, with a lease term | Lower, since selling takes time and costs money |
| Equity | None | Builds with each payment and any appreciation |
| Best for | Stays under 5 years or building savings | Stays of 5 years or more with stable income |
Sources: rents from Apartment List (October 2026), property tax from Ownwell (median effective rate of 1.25%), and Spyglass Realty calculations. Homeowners insurance is not included.
Renting is cheaper month to month, but ownership stabilizes your housing costs over the long run and builds equity. Run both numbers for your situation before deciding.
Factors to Consider Before Deciding
Deciding whether to buy now or wait goes beyond market headlines. It comes down to your readiness and long-term goals.
- Financial readiness: Review your credit score, down payment savings, and debt levels. Stronger finances mean better mortgage terms.
- Time horizon: If you will be in Austin at least five years, buying may be worthwhile. If relocation is likely, renting may be more practical.
- Neighborhood dynamics: Real estate is hyper-local. One area may stay competitive while another sees discounts from oversupply.
- Rent vs. own math: Compare your rent with a projected monthly payment, including taxes and insurance.
- Economic outlook: Watch inflation, job growth, and Federal Reserve policy, which directly affect mortgage affordability.
Expert Tips for Navigating Austin's Market
Preparation matters. Working with a real estate professional helps you read neighborhood-level trends and find opportunities that citywide numbers hide.
- Leverage local expertise: A knowledgeable Austin agent can point to hidden opportunities and back up offers with comparable sales.
- Get pre-approved early: Knowing your budget gives you confidence and signals you are serious. Ask about rate locks.
- Shop for financing: Compare mortgage lenders and explore rate buydowns and first-time buyer assistance. Even small rate savings matter at 7%.
- Negotiate smartly: Ask for concessions such as repairs, closing cost credits, or a rate buydown.
- Stay market-aware: Track listings, rates, and inventory so you can act quickly when the right home appears.
Above all, set clear goals. Define your must-haves and nice-to-haves, and keep to your budget. A home should enhance your life, not overextend your finances.
Should You Wait or Buy a Home Now?
The Austin market is balanced: prices have softened, inventory is healthy, and buyers can negotiate. The choice is not one-size-fits-all. It is about matching market conditions to your personal readiness.
The case for buying now
Buy now if you:
- Plan to stay in Austin five years or more.
- Have stable employment and income.
- Can afford the monthly payment comfortably, ideally under 28% of gross income.
- Have savings for a down payment plus a six-month emergency fund.
- Found a home that meets your needs in your target neighborhood.
The case for waiting
Wait if you:
- Are unsure about staying in Austin beyond two or three years.
- Need to improve your credit score or save a larger down payment.
- Have concerns about job or income stability.
- Are uncomfortable with today's monthly payment.
- Have not found the right home yet.
Buying in Austin should feel exciting, not stressful. Talk to our Austin real estate specialists at 512-640-2077 or contact us here for smart, confident next steps.
Frequently Asked Questions About Buying in Austin Now or Waiting
Is now a good time to buy a house in Austin?
It depends on your timeline and finances, but buyers have more leverage than during the 2021-2022 boom. Homes in the City of Austin closed at 93.3% of list price in August 2026, and active listings are plentiful. The tradeoff is borrowing costs: the average 30-year mortgage rate was 7.40% in early October 2026, up from 6.30% a year earlier (Freddie Mac). If you plan to stay five years or more and can afford the payment comfortably, buying can make sense.
Will Austin home prices drop in 2026?
Forecasts point to further softness. Zillow projected in May 2026 that Austin home values would fall about 4.6% through March 2027. Recent data is mixed: the metro median fell 6.4% year over year in August 2026 to $412,000, while the City of Austin median was $560,000. Forecasts are often wrong, so treat them as one input.
Will mortgage rates go down in 2026?
That is uncertain. The Federal Reserve raised its target rate by a quarter point on September 16, 2026, to 3.75%-4.00%, and called inflation elevated. Mortgage rates are not set by the Fed directly, but they have risen, averaging 7.40% in early October. Many buyers plan around today's rate and refinance if rates fall later.
Is Austin a buyer's market?
Austin leans balanced, with buyers holding more leverage than in recent years. Based on 4,554 active listings and 844 August closings in the City of Austin, supply is roughly five and a half months, which is a calculation we made. Buyers can negotiate on price, repairs, and closing cost credits, but desirable homes in well-located neighborhoods still sell quickly.
Is it cheaper to rent or buy in Austin?
Renting is cheaper month to month. A one-bedroom rents for about $1,174 and a two-bedroom about $1,429 (Apartment List, October 2026), while principal and interest alone on a $550,000 home with 20% down is about $3,046 at 7.40%. Owning builds equity and fixes your payment, so the better choice depends on how long you will stay.
How much income do you need to buy a home in Austin?
Using the common guideline of keeping housing costs under 28% of gross income, a $550,000 home with 20% down at 7.40% needs roughly $155,000 a year in household income to cover principal, interest, and property tax. A lower price, a larger down payment, or a lower rate reduces that figure.
Sources: Freddie Mac, InvestingLive (FOMC decision), Hoodline (Unlock MLS and Redfin), CultureMap Austin (Unlock MLS and Austin Board of Realtors), Hoodline (Zillow forecast), Redfin Dallas, Apartment List, Ownwell, BLS. Figures change often. This article is for general education and is not financial advice. Last updated October 2026.